Table of Contents
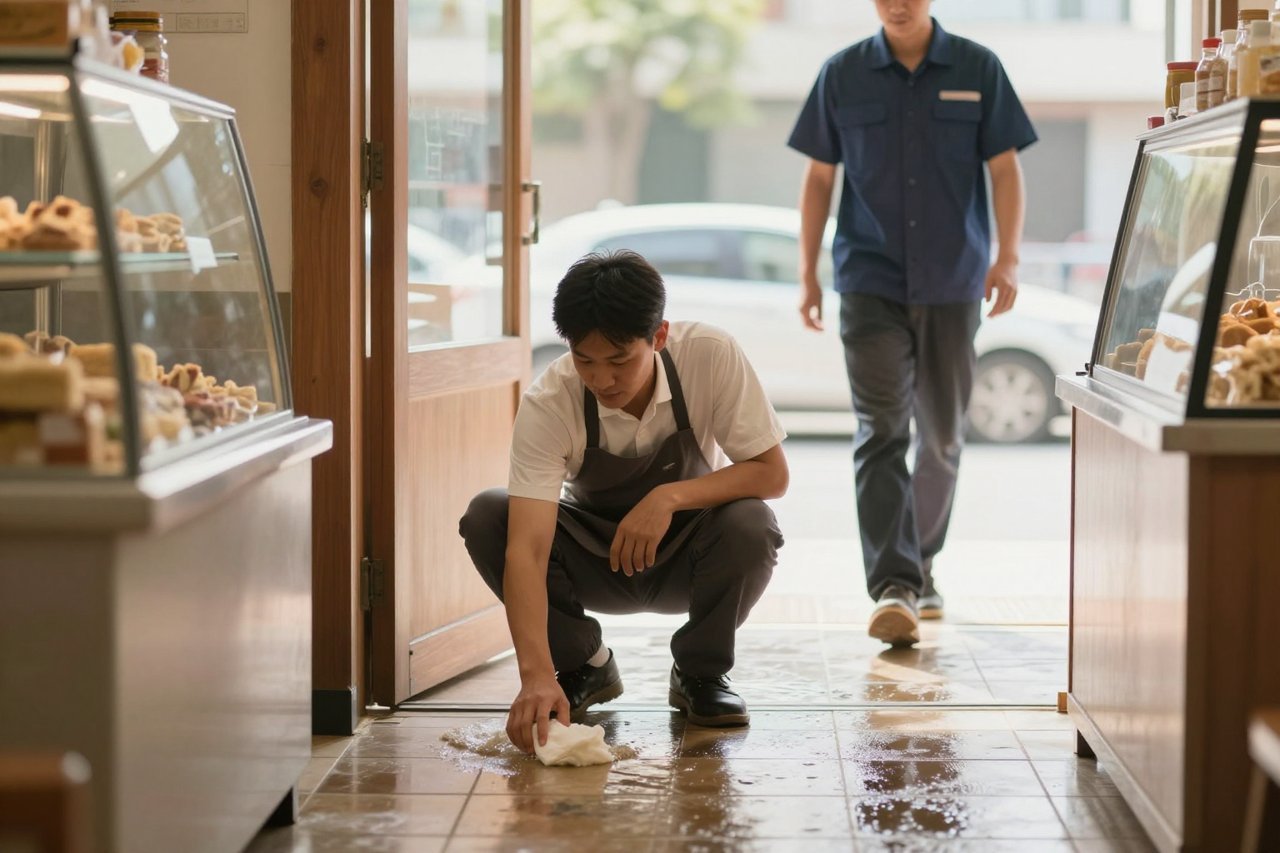
Denise runs a bakery with six employees. One morning a delivery driver walked down her wet back hallway, slipped on the tile, and fractured his wrist. Medical bills and lost wages came to $34,000. Her general liability policy paid the claim minus a $500 deductible. Without it, that money would have come out of the register, and probably the following month’s too.
What caught her off guard wasn’t the slip. It was how many other problems the incident almost created, and how many of them general liability would never have touched.
What General Liability Insurance Actually Covers
General liability, usually shortened to GL, handles the moment your business hurts someone or damages property that belongs to someone else. It’s the policy a landlord wants to see before handing over the keys, and the one a general contractor demands before a subcontractor sets foot on a job site.
A standard policy reads $1 million per occurrence and $2 million aggregate. That means up to $1 million for any single claim and $2 million across the full policy year. Most small businesses buy exactly those limits and rarely think about them again.
The four pieces inside a standard policy
- Bodily injury. A customer trips over a floor mat, a visitor gets clipped by a falling shelf, a client’s employee pulls a muscle helping you move equipment.
- Property damage. You knock out a client’s server while running cable, or your crew cracks a marble lobby floor hauling materials through.
- Personal and advertising injury. Claims of libel, slander, or copyright infringement tied to your marketing, including the ad copy you wrote yourself.
- Medical payments. Small no-fault payments, often $5,000 to $10,000, that cover minor injuries without anyone having to prove you were at fault.
Defense costs sit either on top of those limits or inside them, depending on the policy form. Read that detail before you buy. A $1 million limit that includes defense can be eaten down fast by attorney fees, and a two-year lawsuit burns through six figures of legal spend without a single payout reaching the claimant.
What General Liability Will Not Pay For
This is where owners get burned, and it usually isn’t the insurer’s fault. The exclusions are printed in the policy. Most people simply never read them.
Mistakes in your work are the big one. If a bookkeeper files a client’s taxes wrong, or a consultant gives advice that costs a client a contract, GL does not respond. That’s an errors and omissions problem, and the two coverages solve genuinely different things. If your business sells expertise rather than a physical product, professional liability insurance is probably the policy you need to sort out first.
Injuries to your own employees land under workers’ compensation. Damage to your own building, tools, or inventory belongs to commercial property. Harassment and wrongful termination lawsuits need employment practices liability. Anything that happens on the road, whether it’s a company truck or your personal car used for deliveries, belongs to commercial auto. Your personal auto policy excludes business use, so a fender bender in a work van isn’t covered by the policy you bought for your commute. That’s worth remembering whether you drive for a living or you’re comparing budget carriers like the ones covered in this look at The General auto insurance.
Contractors face one more trap: the your-work exclusion. Build a deck that collapses because of how you built it, and the cost of rebuilding that deck is typically yours. GL covers the damage the collapse causes to other things, not the defective work itself.
What a Policy Actually Costs
Pricing swings wildly by industry. A solo photographer working from a home studio might pay $500 a year for $1M/$2M. A consultant in an office, roughly the same. A restaurant with a busy dining room can pay $3,000 to $6,000. Roofers, electricians, and anyone working at height often land between $2,500 and $8,000, sometimes more with claims history or uninsured subcontractors on the books.
Underwriters look at annual revenue, payroll, square footage, foot traffic, your state, and how many years you’ve gone without a claim. Subcontracted work matters more than most owners realize. Hire people who aren’t insured and their risk becomes your rate.
The fastest way to cut the bill is bundling. A business owner’s policy packages general liability with commercial property for one premium that usually runs 10% to 25% cheaper than two standalone policies. It’s the standard starting point for small operations, though it isn’t right for every one. Figuring out what your business actually needs from commercial insurance comes down to whether you own a building, hold inventory, or work mostly off-site.
Who Needs Coverage, and Who Only Thinks They Don’t
- Anyone with a location customers visit. Retail shops, salons, gyms, clinics, restaurants. Foot traffic equals slip-and-fall exposure.
- Contractors and trades. General contractors want a certificate of insurance before you start. No COI, no work.
- Landlords and property managers. Tenant lawsuits and injuries in shared hallways, stairwells, and parking lots land on you.
- Online and home-based businesses. A marketing agency can be sued over ad copy. A homeowner’s policy excludes business activity, and the personal lines programs you may already carry through AARP insurance won’t step in either.
- Event organizers and anyone renting space. Venues almost always require a certificate naming them as an additional insured.
The common thread is contact with other people’s bodies, property, or reputations. If your business touches any of the three, you have exposure, even if you work alone from a spare bedroom.
What Actually Happens After a Claim
Report it immediately, even if it looks minor. A delay can hand the insurer grounds to deny coverage. Write down what happened, photograph the scene, and keep the report factual. Don’t admit fault, and don’t promise to cover someone’s medical bills out of pocket. A $300 goodwill offer can undermine a defense the insurer would otherwise mount.
From there the carrier assigns an adjuster, investigates, and decides whether to settle or fight. When the claim falls inside your limits, the insurer controls that decision. You don’t get to insist on a trial, and you don’t get to insist on a fast settlement either.
Keep claim files for at least five years. A wrist fracture can take a while to produce a lawsuit, and you may need the paperwork long after you’ve stopped thinking about it.
Lowering the Premium Without Gutting the Coverage
- Raise the deductible from $500 to $2,500 and watch the annual premium fall 10% to 20%.
- Double-check your classification code. An office rate is far cheaper than a construction rate, and a misclassification in your favor is worth correcting at renewal.
- Pay annually rather than monthly to skip installment fees, which often add 5% to 10%.
- Document safety training, incident logs, and maintenance schedules. Insurers discount businesses that can prove they manage risk.
- Verify every subcontractor carries their own GL policy, and collect new certificates each year, not just at hiring.
- Shop the market every two or three years. Rates move, and a carrier that looked expensive in 2022 may be the cheapest option on your desk today.
Matching Limits to the Contracts You Sign
Before you sign anything, read the insurance requirements section line by line. A $1M/$2M policy satisfies most commercial leases, but larger clients ask for $2M/$4M, additional insured status, a waiver of subrogation, and primary and noncontributory language. Those endorsements cost extra. They’re still cheap compared to losing a contract you already counted on.
Then look in the other direction. If your own agreements require subcontractors to carry $1 million, collect the certificate and check the expiration date. One uninsured sub with a ladder and a bad day turns into your claim, your premium increase, and an awkward renewal conversation.
A local independent agent who writes policies for businesses in your specific trade will know which carriers are competitive and which exclusions to flag. That conversation takes about an hour and routinely saves far more than it costs. If it’s been more than two years since you last reviewed your limits, the numbers on your policy almost certainly no longer match the size of your business.