
Table of Contents
A repossessed car is one of the few places left where a private buyer can realistically beat dealer forecourt prices. Banks and credit unions don’t want to be in the used-car business. They want the loan balance recovered, the vehicle gone, and the file closed. That urgency is your margin.
It’s also where people get burned. Auction lots are noisy, cars sell in under 90 seconds, and nobody is going to tell you the transmission slips on the drive home. The buyers who do well treat it as a sourcing exercise rather than a shopping trip — they check the paperwork, run the numbers, and walk away more often than they bid.
What a Repossessed Car Actually Is
A repo is a vehicle a lender has seized after the borrower defaulted and sold to recover the outstanding balance. That’s it. It isn’t a salvage car, and it isn’t a police impound, although the three get lumped together online.
Most repos are three to eight years old, complete with a lien release and a clean title. What varies wildly is condition. Someone who stopped paying their loan often stopped servicing the car too — bald front tyres, a check-engine light nobody cleared, a boot full of the previous owner’s belongings. A bank rep will note ‘runs and drives’ on the sheet and move on to the next unit.

That’s the gap you’re exploiting: a distressed seller with no emotional attachment to the car and a limited interest in maximising the price. Distressed assets reward people who show up prepared, the same instinct covered in awakening your inner vulture investor.
Where Repossessed Cars Are Sold
Lender and credit union sales
Smaller banks and credit unions often hold monthly sales in their own car park with 10–30 vehicles. Registration is usually free or costs $25, bidding is slow, and there’s a genuine chance of a bargain because fewer dealers turn up. Call five local credit unions and ask whether they sell repossessed collateral directly. This is the least competitive channel in the market.
Trade-only auction houses
Manheim and ADESA are wholesale operations. You need a dealer licence, or you pay a licensed broker a flat fee (typically $300–$500) to bid on your behalf. Worth it if you’re chasing a specific model, because the volume is enormous and the vehicles have already been through a basic inspection.
Public and online liquidation platforms
Copart, IAA, GovDeals, GSA Auctions and dozens of regional auctioneers sell lender-repossessed stock to the public. You’ll register, upload ID, and place a refundable deposit. Read the fee schedule before you get excited: buyer’s premiums of 5–10%, admin charges of $50–$200, and storage billed daily from the moment you win.
Dealer forecourts
Most independent dealers buy at trade auctions and resell with a markup. You’ll pay 20–30% more, but you get a warranty, a valeted car, and someone to complain to. For a non-mechanical buyer, that premium is often money well spent.
The Real Numbers Behind the Saving
Auction listings love to advertise repos at ‘30% below book’. That figure usually predates the fees. A $14,000 hammer price can turn into $15,600 by the time you’ve paid a 7% buyer’s premium, a $180 admin fee, $60 in documentation, and three days of storage because your bank transfer was slow.
Budget for a $500–$1,500 catch-up service too: fresh fluids, brake pads, maybe a battery and a set of tyres. A realistic all-in saving against a dealer car is 10–20%, which is still meaningful on a $15,000 purchase.
Timing matters as much as anything. Used car values move in cycles, and lender repos flood the market when loan defaults spike — often the same months retail prices soften. Reading the market properly, as explained in why used car prices rise and fall, puts you at the auction on a good week instead of a desperate one.
Homework Before You Register
Every serious bidder runs the same checklist before placing a single offer:
- Pull the VIN and buy a vehicle history report. $10–$30, and it flags salvage titles, odometer rollbacks, outstanding finance and write-off histories the auction may not mention.
- Read the condition grade carefully. ‘Run and drive’ means it moved onto the lot under its own power. ‘Engine start’ means it started but may not drive. ‘Stationary’ or ‘non-runner’ means exactly what it says.
- Study the photos at full size. Look for mismatched paint on one panel, uneven tyre wear, a warning light cluster lit up on the dash, or a steering wheel with 200,000 miles of shine on it.
- Set a walk-away number before the auction starts. Write the total — hammer price plus fees plus repairs — and stick to it. Auction adrenaline is real and it costs money.
- Confirm the paperwork situation. Ask when the title will be released. Doc fees vary, and a delayed title can leave you with an unregistered car for 60 days.
Auction Day, Step by Step
Arrive 90 minutes before the first lot. Public viewings are short and crowded, and you’ll want time with the car.
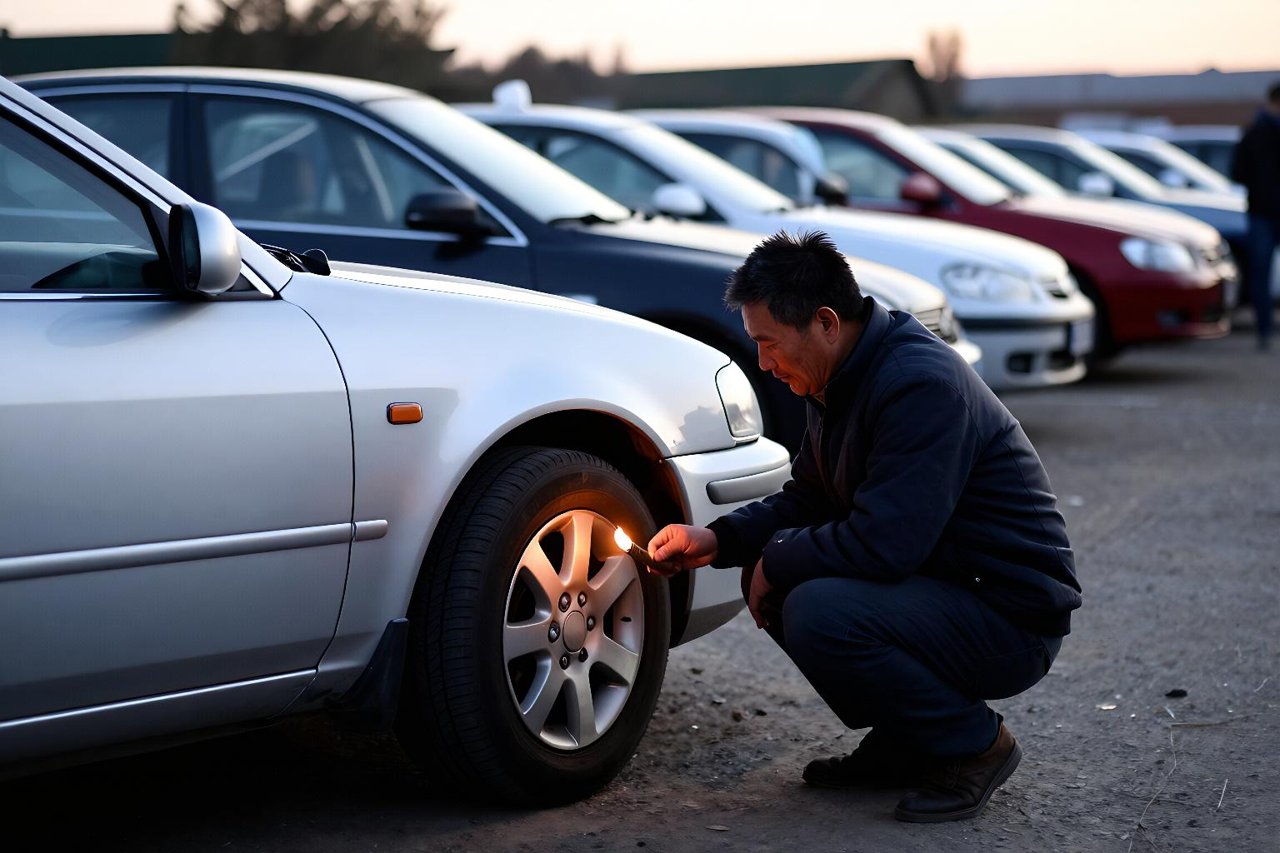
Bring a torch, a tyre tread gauge, and a $25 OBD-II scanner. If the auction permits starting vehicles — many only allow a jump-pack start, some don’t allow it at all — plug in the scanner and pull the codes. A pending misfire code will tell you more in ten seconds than an hour of staring at the engine bay. Check panel gaps, look underneath for fresh oil or coolant drips, sniff the interior for smoke or damp, and confirm how many keys are present. One key means a $200 trip to a locksmith later.
Auctioneers move at 60–90 seconds per vehicle. Ties go to the earliest bid, pre-bids placed online can be beaten, and the online simulcast usually lags the room by a second or two. If you’re bidding remotely, decide your maximum in advance and use the platform’s max-bid function rather than clicking live.
Mistakes That Cost Buyers Real Money
Nearly every expensive repo story comes down to one of these. Bidders forget that ‘as-is, where-is’ means there is no comeback — once the gavel falls, every fault is yours, including the ones the listing didn’t mention.
Others miss that some states require the seller to provide an emissions certificate that an auction won’t have, so the car can’t be registered until you’ve paid for repairs. Or they win a vehicle with a rebuilt title, which halves its resale value and makes it hard to insure.
Financing trips people up too. Most repo auctions want certified funds within 24–48 hours, and many lenders won’t write a car loan against an as-is auction vehicle. If you need credit, arrange a pre-approval with a credit union first and confirm in writing that they’ll lend on a repo purchase. And sort insurance before collection day — you can’t legally drive off the lot without it.
The First Week With Your New Car
Collect the bill of sale, the lien release and the title or title application. Then book a full service: engine oil, transmission fluid, coolant, brake fluid, filters, and a brake inspection. Repos rarely come with service records, so assume nothing has been done for 12 months.
Get a state inspection or roadworthy check done in the first few days rather than the first month. It’s better to discover a worn ball joint on day three, while you still have budget set aside, than on a motorway slip road at 70mph. Expect to spend a few hundred pounds or dollars on top of the purchase price and you’ll rarely be disappointed — most repo cars turn out to be sound, just neglected.


