
Table of Contents
A renters policy is easy to ignore until the night a supply line bursts under the kitchen sink and you’re standing in an inch of standing water at 11pm, holding a laptop that was on the floor. That’s the moment the $16 monthly charge stops being an abstract line item and turns into something you need to operate correctly. Most people have never filed a claim before, which is exactly why so many of them leave money on the table.
What Your Policy Actually Pays For
Standard renters coverage is written on what insurers call the HO-4 form, and it splits into four pieces worth understanding before you call anyone.
- Personal property (Coverage C). Your belongings, usually set at 50–70% of the total policy amount. A $30,000 policy typically means $15,000–$21,000 of contents coverage.
- Loss of use. Hotel bills, takeout, and laundry while your unit is unlivable. Usually 20–30% of your contents limit, so roughly $3,000–$6,300 on that same policy.
- Personal liability. $100,000 is the common floor. It covers you if you flood the unit below or a guest trips on your rug and sues.
- Medical payments to others. Smaller, often $1,000–$5,000, and it pays regardless of who was at fault.
Your deductible applies once per claim, not once per item. A $750 deductible on a $3,200 laptop replacement means you collect $2,450, assuming you carry replacement cost coverage rather than actual cash value.
The First 24 Hours Matter More Than the Paperwork
Adjusters can tell within about thirty seconds whether a claim is going to be straightforward. What tips it is whether the evidence still exists when they look.

- Stop the damage from spreading, then stop. Shut off the water, move electronics off the wet floor. Keep every receipt for a wet-vac rental or a box fan.
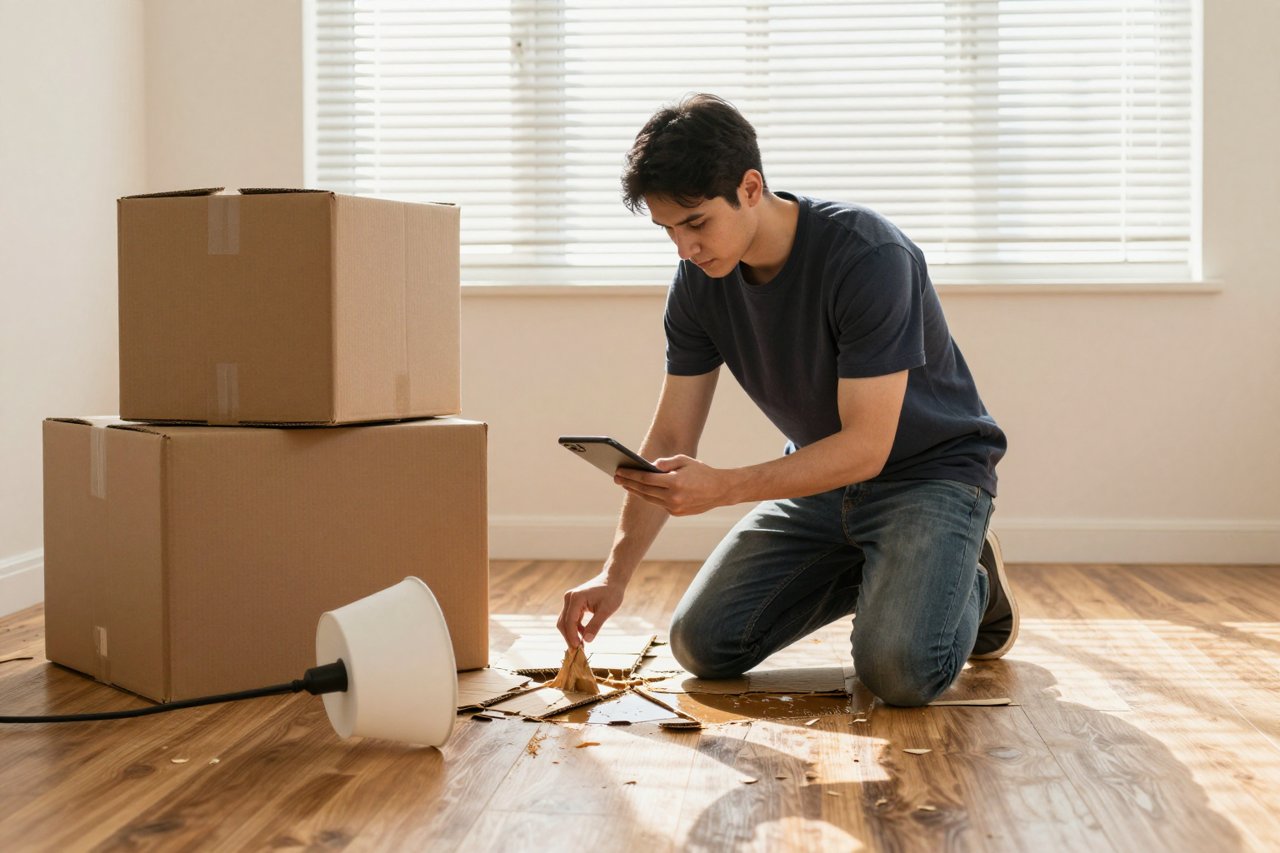
- Photograph before you clean. Wide shots of each room, then close-ups. Put a coin or a ruler next to anything whose size matters.
- Don’t haul the ruined couch to the curb. Adjusters want to see salvage value with their own eyes. Pile damaged items in the garage or a corner.
- Get a police report for any theft. Nearly every insurer asks for one, and it’s the single most common missing document in stolen-property claims.
Call your landlord the same day, but understand you’re making two separate notifications. Structural damage belongs to their policy.
Filing the Claim: What You’ll Be Asked For
The intake call is short. The follow-up is where claims stall, because that’s when you’re asked to produce documentation most renters never kept.
Documents that move a claim forward
Expect to hand over the date and cause of loss, your lease or another proof of residence, photos or video of the damage, purchase receipts or bank statements for big-ticket items, and an itemized list with make, model, and serial numbers. If you bought a $2,000 camera two years ago and can dig up the card statement, the claim is basically done. If you can’t, the adjuster will settle on a depreciated estimate they choose.
How long it takes
A simple contents claim with clear photos often lands between 5 and 14 days after inspection. A full apartment inventory with 80 line items can run 30 to 60 days. Water losses that involve both you and the building owner drag longer because two adjusters have to agree on causation. States set prompt-payment deadlines, typically 15 to 45 days after proof of loss, so you have a clock to point to if things go quiet.
Sub-Limits: Where Large Claims Quietly Get Cut
You can buy $20,000 of contents coverage and still collect $1,500 for a stolen engagement ring. Policies cap entire categories regardless of your total limit, and the caps are smaller than people expect.
Jewelry and watches usually cap at $1,000–$2,500 for theft. Cash sits around $200. Bicycles often top out near $1,000–$1,500 for theft, and silverware around $2,500. Electronics are inconsistent: some carriers treat computers as ordinary contents, others cap them. Our breakdown of renters insurance for valuable electronics walks through where those ceilings bite, and what a policy really pays for jewelry explains why scheduling an item is often the only fix.
Theft claims have their own trapdoors, including proof-of-ownership rules and mysterious-disappearance exclusions that insurers apply aggressively. There’s a reason theft claims fall apart in predictable places, and almost all of them involve documentation rather than the loss itself.
Replacement Cost vs. Actual Cash Value Is a Four-Figure Difference
Actual cash value pays today’s price minus depreciation. Replacement cost pays what it costs to buy the item new. On a four-year-old $1,200 sofa, ACV might come in around $480. If you paid for the replacement cost endorsement, you get closer to the full retail figure, often after you prove you replaced it.
Check which one you have before you file, not after. The difference on a full apartment of furniture, clothing, and kitchen gear routinely runs into several thousand dollars.
When the Landlord’s Policy Is the One That Pays
Renters tend to assume the building’s insurance covers their belongings. It doesn’t. The landlord’s policy repairs the structure, the fixtures, and the common areas. Your couch, your clothes, and your laptop are yours to insure.
Liability is where the lines cross. If your overflowing tub damages the unit below, your liability coverage responds. If the building’s own plumbing fails, that’s the owner’s claim, though you still file separately for your contents. Landlords can require you to carry coverage, but there are limits on what they can demand; what landlords can actually require covers the specifics, including why a $500,000 liability demand in a lease isn’t automatically enforceable.
Denials, Partial Denials, and What to Do Next
Most denials trace back to one of four things: an excluded cause (flood, earthquake, rodents, mold from long-term neglect), late notice, a misstatement on the application, or damage the insurer classifies as maintenance neglect.
Ask for the denial in writing with the specific policy language quoted. Then get an independent repair estimate, which frequently contradicts the adjuster’s scope. If the number still looks wrong, file a complaint with your state insurance department. It costs nothing, takes about fifteen minutes online, and carriers respond because regulators track the volume. App-based insurers tend to resolve disputes faster simply because the photo trail is already in their system; our Lemonade renters insurance review covers how that claims flow works in practice.
Build the File Before You Need It
Spend twenty minutes this weekend walking through your apartment with your phone on video. Open closets, narrate what you see, and pan across the desk. Then photograph the serial plate on your TV, your bike’s frame number, and the back of any camera gear. Upload the video somewhere it survives a fire.
Forward purchase confirmation emails into a single folder labeled with the item name. When a claim happens, you’ll be able to hand an adjuster a documented inventory instead of a rough estimate from memory. That single habit is usually worth more than any upgrade you can buy at renewal, and it costs nothing but the twenty minutes.


