
Table of Contents
Two people walked into the same garden centre on a wet Tuesday in March. One left with a bag of compost. The other left with a fractured wrist, a £1,400 physiotherapy bill and a phone full of photographs of a floor nobody had mopped. That second person had the makings of a public liability claim — and whether it succeeded had almost nothing to do with how obviously wet the floor was, and everything to do with what she did in the twenty minutes after she fell.
Public liability claims sit where everyday accidents collide with business insurance. They cover injuries and property damage caused by a business, organisation or individual to a member of the public. Not to their own staff. Not to another driver on a public road. Everything else is broadly fair game, which is exactly why the process confuses people.
What a public liability claim actually is
Strip away the jargon and it’s a demand for compensation made against whoever was legally responsible for the place, activity or situation that caused harm. The engine underneath is negligence. Four things have to line up:
- Someone owed you a duty of care — a shop, a landlord, an event organiser, a tradesperson in your home.
- They breached that duty, usually by falling below the standard a reasonable operator would meet.
- The breach caused your injury or damage.
- The injury has a cost you can put a number on.
Break any link in that chain and the claim collapses, no matter how badly hurt you were. A wet floor that nobody could reasonably have known about is not negligence. A wet floor with no cleaning rota, no cones and a manager who was told about it an hour earlier usually is.

Who ends up on the other side of a claim
Defendants are more varied than most people expect. Supermarkets and pubs, obviously. Also gyms with slick changing-room tiles, holiday parks, landlords of rented flats, sports clubs, wedding venues, contractors working at height near a public footpath, and local authorities responsible for pavements that have been crumbling since the last budget round.
The occupier’s duty to visitors
Much of this territory is occupiers’ liability — the principle that whoever occupies a premises owes a duty of care to people lawfully on it, and a lesser duty even to trespassers. The specifics matter enormously, from the state of the flooring to the adequacy of lighting, signage and inspection records. If your accident happened on someone else’s property, it’s worth understanding how premises liability is assessed and who really pays when you slip, trip or fall, because the evidence insurers want is different from what most claimants assume.
The incidents that generate the most claims
Certain patterns repeat across thousands of cases. Slips on wet or greasy flooring near entrances, food counters and toilets. Trips over uneven paving, raised kerbs and loose matting. Injuries from falling stock, unsecured shelving or a badly stacked pallet in an aisle. Lacerations from broken glass that staff knew about. Burns from a hot water urn at a self-service counter.
Animal incidents are a category of their own. A delivery driver bitten by a customer’s dog has a claim against the householder’s insurance, and the rules differ sharply depending on where it happened — state dog bite laws determine who pays when a dog bites, including whether the owner’s prior knowledge of aggression matters. Injuries caused by defective equipment or unsafe goods sit in a slightly different lane, covered below.
Property damage claims are common too, and often undervalued. A contractor’s ladder through your car windscreen, a burst pipe from the flat above ruining a laptop and a carpet, a hire company’s equipment that damaged your driveway.
Evidence is what separates a claim from a complaint
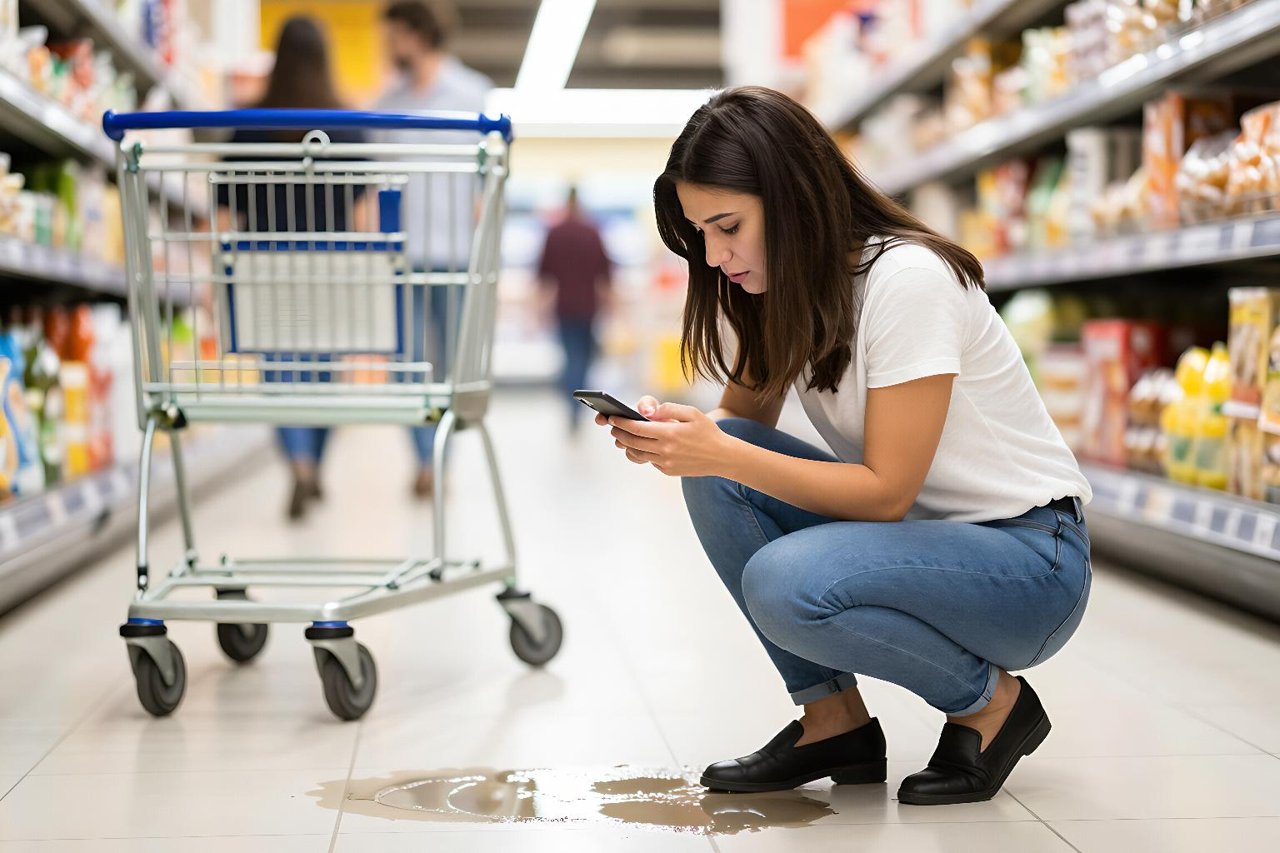
Insurers do not pay for sympathy. They pay for documentation. The garden centre claimant above took twelve photographs in the first ten minutes, including two of the absence of any warning cone. She asked for the incident book to be completed and photographed the entry. She got the names and phone numbers of two witnesses before they left. Then she went to A&E and kept every discharge note, receipt and appointment letter.
Compare that with the far more common version: a fall, a bit of embarrassment, a taxi home, and a call to a solicitor three weeks later with no photographs, no witnesses and a healing bruise.
What to gather in the first 48 hours
- Photographs and video of the hazard, the surrounding area and your injury, with timestamps intact.
- The incident reference number and the name of whoever took your report.
- Witness names, phone numbers or email addresses — not just first names.
- A written note of what happened while your memory is fresh.
- A request that CCTV of the area be preserved. Footage is often overwritten within 30 days, and it’s frequently the difference between a settled claim and a denied one.
Inside the insurance process
The business passes your claim to its public liability insurer, which appoints a loss adjuster to investigate. Expect requests for medical records, proof of earnings if you’re claiming lost income, and a statement. The insurer will look hard at causation — did the injury happen the way you say? — and at contributory negligence, meaning the extent to which your own carelessness reduced the payout. A claimant who was running in flip-flops through a darkened yard may see an offer cut by 25% or more.
Most cases settle without court proceedings. Straightforward falls with clear liability often resolve in three to nine months. Disputed liability, ongoing medical treatment or a serious injury can stretch to two or three years. The step-by-step mechanics are broadly the same whatever the incident, and this walkthrough of how personal injury claims move from the scene of the accident to the settlement check is a useful map for the timeline.
Watch the clock. Injury claims in England, Wales and Scotland generally have a three-year limitation period from the date of the incident; property damage claims in Scotland run to five. Most US states use two or three years, with rules for minors and people lacking capacity that can pause the deadline. Miss it and the claim is dead regardless of merit.
Where public liability ends and other claims begin
Getting the category right matters, because the defendant and the insurance policy behind them change. If a faulty escalator or a badly maintained machine hurt you, that’s still occupiers’ liability. If a product you bought failed and injured you, you’re looking at a different framework entirely — one where product liability rules decide who pays when the thing you bought breaks you, potentially reaching the manufacturer, importer or retailer rather than the shop where you were standing.
The same applies to a defective kettle that scalded you versus a kettle that was fine but left in a dangerous spot by staff. One is a product claim, one is public liability, and they can occasionally run side by side. The practical steps for the product version are set out in this guide to defective product claims and what to do when something you bought turns on you.
Injuries to employees fall under employers’ liability. Crashes involving vehicles on public roads go through motor insurance. A vehicle that hits you in a private car park can straddle both.
What compensation covers, and the limits that decide everything
General damages pay for pain, suffering and loss of amenity — the effect on your life rather than your bank account. Special damages reimburse measurable losses: treatment, travel to appointments, prescription charges, care costs, and lost earnings including overtime and future earnings where the injury has lasting impact. A minor soft-tissue injury might be worth a few thousand. A wrist fracture needing surgery and physio often lands between £6,000 and £15,000 in the UK, before lost income is added.
Then there’s the insurance cap. Most UK public liability policies carry £2 million to £10 million of cover, and £5 million is common for small commercial premises. US general liability policies typically start at $1 million per occurrence. Those figures sound enormous until a catastrophic injury produces a claim that exceeds them — at which point the business’s own assets come into play, and a business without adequate cover may simply have nothing to recover.
If you’re the one being claimed against
Three rules. Notify your insurer immediately, even if you think the claim is baseless — late notification is the most common reason a policy responds with a refusal. Don’t admit liability, in writing or in conversation, however apologetic you feel. And preserve everything: CCTV, maintenance logs, cleaning records, staff rotas, the actual piece of equipment involved. A hazard that was fixed within an hour of the accident looks like diligence; the same hazard quietly removed the next morning and undocumented looks like concealment.
When to bring in a solicitor, and what it costs
You can pursue a small, clean-cut claim yourself, and some people do. Once there’s a disputed version of events, a pre-existing condition complicating causation, or an injury likely to affect your work, professional involvement usually pays for itself. Most personal injury solicitors in the UK work on conditional fee agreements — no win, no fee — with the success fee capped at 25% of the compensation, and after-the-event insurance covering the risk of losing. In the US, contingency fees typically run 33% to 40%.
Ask any solicitor three questions before signing: what the fee will be in cash terms on a £10,000 settlement, who pays for medical reports, and whether they’ll fund court fees if the insurer refuses to budge. A good one will answer all three without hesitating.


